FTAsiaEconomy Updates by FintechAsia can be understood as a topic focused on developments connecting financial technology, economic activity, and digital business across Asia. Readers interested in this subject can explore how payment systems evolve, how financial institutions adopt new technologies, and how regulations influence the development of fintech products. It is important to distinguish the general subject from independently verified financial data: a trend article can explain market developments, but investors should confirm specific figures, company announcements, and policy changes through authoritative sources before making decisions. Fintechasia+1
The subject is particularly relevant because Asia includes financial markets at different stages of digital development. Singapore has an established international financial ecosystem, India has extensive digital payment infrastructure, and Southeast Asian countries are developing connections between their domestic payment networks. These markets do not follow an identical path, so a strategy that works in one country may require different partnerships, technical systems, or regulatory approvals in another. Understanding these differences helps businesses make better decisions about expansion, customer experience, and financial risk.
Why Asian Fintech Developments Matter
Financial technology affects much more than banking applications. It influences how online stores receive money, how small businesses manage cash flow, how workers send remittances, and how lenders assess applications. Faster digital transactions can reduce administrative work, while data-driven services can help businesses understand customer needs and manage operational costs. However, these benefits depend on reliable infrastructure, appropriate consumer safeguards, and responsible use of financial data.
For entrepreneurs and investors,FTAsiaEconomy Updates by FintechAsia following fintech developments can help identify emerging business models and areas that deserve closer research. For ordinary consumers, it can make unfamiliar financial products easier to evaluate. The most useful approach is to look beyond exciting product launches and ask practical questions: Does the technology solve a real problem? Is the provider trustworthy? Are fees transparent? Can the service operate legally in the target market? Those questions provide a stronger foundation for understanding Asia’s evolving digital economy.
10 Key Trends Transforming Asia’s Digital Economy
1. Digital Payments and Mobile Wallets
Mobile Wallet Payment: Apple Pay vs Google Pay for Singapore Merchants – My Framer Site
trynashi.com
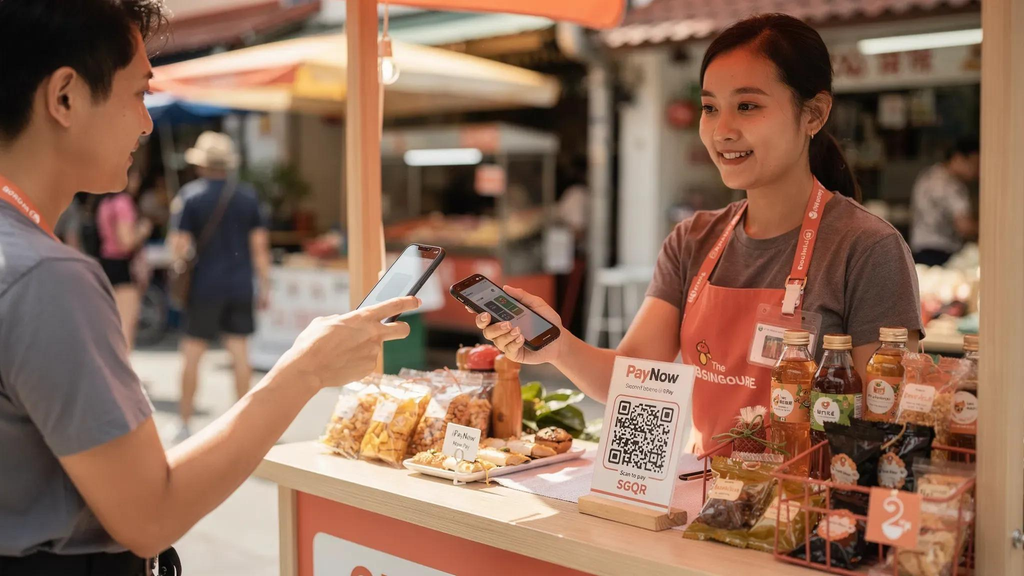
Digital payments remain a central part of Asia’s fintech transformation. Consumers increasingly expect convenient ways to pay for products, transfer funds, and settle everyday bills without relying exclusively on cash. Mobile wallets, QR codes, bank applications, and instant-transfer services give customers more options while helping merchants simplify checkout. Regional systems such as Singapore’s PayNow, Thailand’s PromptPay, and India’s Unified Payments Interface illustrate different approaches to making electronic payments more accessible. 27-29 April 2027+1
For businesses, accepting digital payments can reduce manual reconciliation and make online sales easier to manage. A small retailer may use a QR payment service to receive money, while an e-commerce company may integrate several payment methods to serve customers in different markets. Nevertheless, digital payments are not automatically free or riskless. Transaction charges, settlement delays, technical outages, refund procedures, and fraud protection vary between providers. Businesses should compare these details before selecting a payment partner.
2. Artificial Intelligence in Financial Services
Equity analyst uses AI for earnings research to assess stock market value
Artificial intelligence is becoming an important tool for financial institutions seeking to improve customer service, identify suspicious transactions, and process information more efficiently. AI systems can help analyse transaction patterns, flag unusual account activity, organise customer enquiries, and support certain credit assessments. When implemented carefully, these applications may reduce repetitive work and allow employees to focus on decisions that require human judgment. Industry discussions about Asia-Pacific fintech increasingly include AI adoption alongside digital banking and payment innovation. 27-29 April 2027+1
Consider a payment company that processes thousands of transactions every minute. Reviewing every transaction manually would be slow and expensive, but an automated system can identify patterns that deserve additional investigation. A financial institution might also use an AI-powered assistant to answer routine questions about account services, while directing complicated complaints to trained staff. These applications can improve efficiency, although their actual performance depends on data quality, system design, and ongoing monitoring.
3. Cross-Border Payments and Remittances
International money transfers are essential to businesses, families, freelancers, and migrant workers throughout Asia. Yet moving funds between countries can involve foreign-exchange costs, intermediary institutions, different operating hours, and complicated compliance requirements. Cross-border payment initiatives aim to improve this process through better technical connections, coordinated payment networks, and more efficient settlement arrangements. Regional payment-linkage efforts are particularly relevant as travel, online commerce, and international business continue to connect Asian markets. 27-29 April 2027+1
For example, a small business selling products to customers abroad needs to receive payments predictably and understand how much money will arrive after fees and currency conversion. A worker sending money to family members needs a service that clearly displays the exchange rate, transfer charge, delivery estimate, and recipient requirements. Digital remittance services may simplify these tasks, but available features differ by country and provider.
4. Digital Banking and Financial Inclusion
Asian Woman uses a smartphone and credit card with a laptop for secure online shopping, highlighting mobile banking, digital payments, and convenient e-commerce transactions at home.
Digital banking is changing how people access financial services by allowing many routine activities to take place through mobile applications and websites. Customers can check balances, review transactions, transfer money, and manage eligible financial products without visiting a physical branch. For people living far from traditional banking facilities, these services can reduce travel time and make everyday financial tasks easier. Digital banking can also help businesses manage accounts and payments across multiple locations.
5. Embedded Finance and Open Banking
Embedded finance brings financial services into platforms that customers already use. Instead of visiting a separate banking website, a customer might access an eligible payment option while shopping online, arrange financing through a participating marketplace, or purchase insurance during a booking process. This approach can reduce friction because the financial service appears at the point where the customer needs it. Across Asia, embedded finance and partnerships between traditional banks and technology businesses are important areas of fintech development. 27-29 April 2027+1
Open banking and open finance can support related services by enabling authorised data sharing through regulated arrangements and technical interfaces. With appropriate customer permission, a financial application may be able to access selected information from another institution to provide account insights or support an application. FTAsiaEconomy Updates by FintechAsia The precise rules and available services differ across jurisdictions, so businesses must confirm local requirements before launching these products.
6. Blockchain, Stablecoins, and Tokenisation
Blockchain technology provides a shared digital recordkeeping structure that can support certain types of financial transactions. In fintech, it is being explored for applications involving digital assets, transaction settlement, recordkeeping, and the representation of assets as digital tokens. Stablecoins, which are designed to maintain a relatively stable value against a reference asset, have also attracted attention as financial institutions and payment companies investigate new ways to move money. FTAsiaEconomy Updates by FintechAsia Recent Asian fintech coverage has highlighted institutional experiments with stablecoin payments and digital-asset infrastructure, although availability and legal treatment vary by market. Asia Fintech+1
Tokenisation involves representing rights to an asset through digital tokens. Depending on the structure and applicable law, this may support new approaches to transferring or managing certain financial assets. However, tokenisation does not automatically make an asset liquid, safe, or legally enforceable. The underlying ownership rights, custody arrangements, settlement process, and applicable investor protections all matter.
7. Fintech Investment and Sustainable Growth
Investment helps fintech companies develop products, hire skilled employees, improve security, and expand into new markets. However, funding alone does not demonstrate that a business has a sustainable model. Investors increasingly need to examine how a company earns revenue, retains customers, manages operating expenses, and controls financial risks. Coverage of Asia’s fintech market has highlighted selective funding and greater attention to commercial performance rather than expansion at any cost. Tycoonstory+1
For a fintech startup, this shift can encourage better business planning. Instead of measuring success only through downloads or registrations, management can examine active customers, repeat usage, customer acquisition costs, revenue per user, and the cost of preventing fraud. A company that demonstrates reliable service and a realistic route to profitability may be better positioned to build lasting partnerships. These indicators do not guarantee investment success, but they provide more useful evidence than headline growth figures alone.
8. Cybersecurity and Fraud Prevention
As more financial activity moves online, cybersecurity becomes a fundamental part of customer trust. Financial applications handle sensitive information, account credentials, payment details, and transaction records, making them attractive targets for criminals. Common threats include phishing messages, stolen passwords, impersonation scams, account takeovers, malicious software, and fraudulent payment requests. Even a technically sophisticated financial service can suffer losses if customers are deceived or internal security controls are weak.
Financial institutions can reduce these risks through measures such as multifactor authentication, transaction monitoring, encryption, secure software development, and regular security testing. They should also establish clear incident-response procedures so teams can investigate suspicious activity and communicate effectively when a problem occurs. FTAsiaEconomy Updates by FintechAsia AI may help identify unusual behaviour, but automated detection systems need careful evaluation because legitimate customers can also trigger alerts.
9. Regulatory Changes and Consumer Protection
Financial technology operates within a complex regulatory environment because payment services, lending, digital assets, and banking involve different types of risk. Asian jurisdictions may apply different licensing requirements, identity-verification procedures, data protection standards, and anti-money-laundering obligations. FTAsiaEconomy Updates by FintechAsiaCompanies that operate across borders must understand these differences rather than assuming that approval in one market automatically permits them to offer the same service elsewhere.
Regulation can influence product design, operating costs, partnerships, and expansion plans. A payment provider may need to meet specific requirements before serving customers, while a digital lender may have to follow rules governing disclosures, affordability, and customer treatment. Regulatory sandboxes and structured industry consultations can provide ways to test certain innovations under defined conditions, but participation does not remove every legal obligation. 27-29 April 2027+1
10. Digital Lending and Alternative Credit Scoring
Digital lending uses technology to simplify parts of the loan application, assessment, approval, and repayment process. It can help financial providers serve customers who prefer online applications and may support faster decisions when the provider has reliable information. Traditional credit assessments often depend on established credit histories, but some lenders also explore permitted alternative data to understand applicants who have limited records FTAsiaEconomy Updates by FintechAsia.
For example, a small business may have regular sales but lack the financial history required by a conventional lending process. Where laws and customer permissions allow, a lender might consider verified transaction information alongside conventional financial data. This can provide additional context about the business, although it cannot guarantee that the applicant will repay a loan. Models must be tested carefully to identify inaccurate assessments and unfair outcomes.
How Businesses Can Benefit From These Trends
Businesses can use fintech developments to improve payments, manage cash flow, understand customer behaviour, and simplify administrative work. The best starting point is to identify a specific operational problem instead of adopting technology simply because competitors are doing so. An online business might prioritise reliable payment processing, while a company with international suppliers may focus on transfer fees and foreign-exchange costs.
A practical evaluation should consider the following factors:
- Customer demand: Confirm which payment and financial services customers actually use.
- Total cost: Compare transaction fees, currency-conversion charges, software costs, and settlement terms.
- Security: Review authentication, fraud monitoring, data protection, and incident-response procedures.
- Compliance: Verify licensing, contractual obligations, and relevant local regulations.
- Measurable results: Track changes in transaction success, processing time, operating costs, and customer satisfaction.
Challenges and Future Opportunities
Asia’s digital economy offers substantial opportunities, but its markets are not uniform. Differences in infrastructure, regulation, language, customer behaviour, and purchasing power can complicate regional expansion. Smaller businesses may also lack the budget or technical expertise needed to integrate advanced financial systems, while customers with limited connectivity can remain excluded from digital services.
Another challenge is balancing convenience with privacy and security. Financial platforms collect information that can be valuable for service improvement but must be handled responsibly. AI systems require appropriate oversight, digital assets need clear governance, and payment providers must maintain reliable systems as transaction volumes grow. Failure in any of these areas can damage customer trust and create financial or legal consequences.
Conclusion
FTAsiaEconomy Updates by FintechAsia: 10 Key Trends provides a useful framework for understanding how technology is reshaping financial services across Asia. Digital payments, artificial intelligence, cross-border transfers, digital banking, embedded finance, blockchain, investment, cybersecurity, regulation, and digital lending all influence how businesses and consumers interact with money.
Each trend offers potential benefits, but none is without challenges. Businesses must evaluate costs, security, customer needs, and regulatory requirements before investing in new financial technology. Consumers should understand the risks associated with digital payments, borrowing, and digital assets instead of relying on promotional claims.
Pingback: TablesProWorld com: Content, Purpose & Reliability - Celebrity Profile